The 'Set It and Forget It' Portfolio That Forgot to Warn You
Finance | October 1, 2026
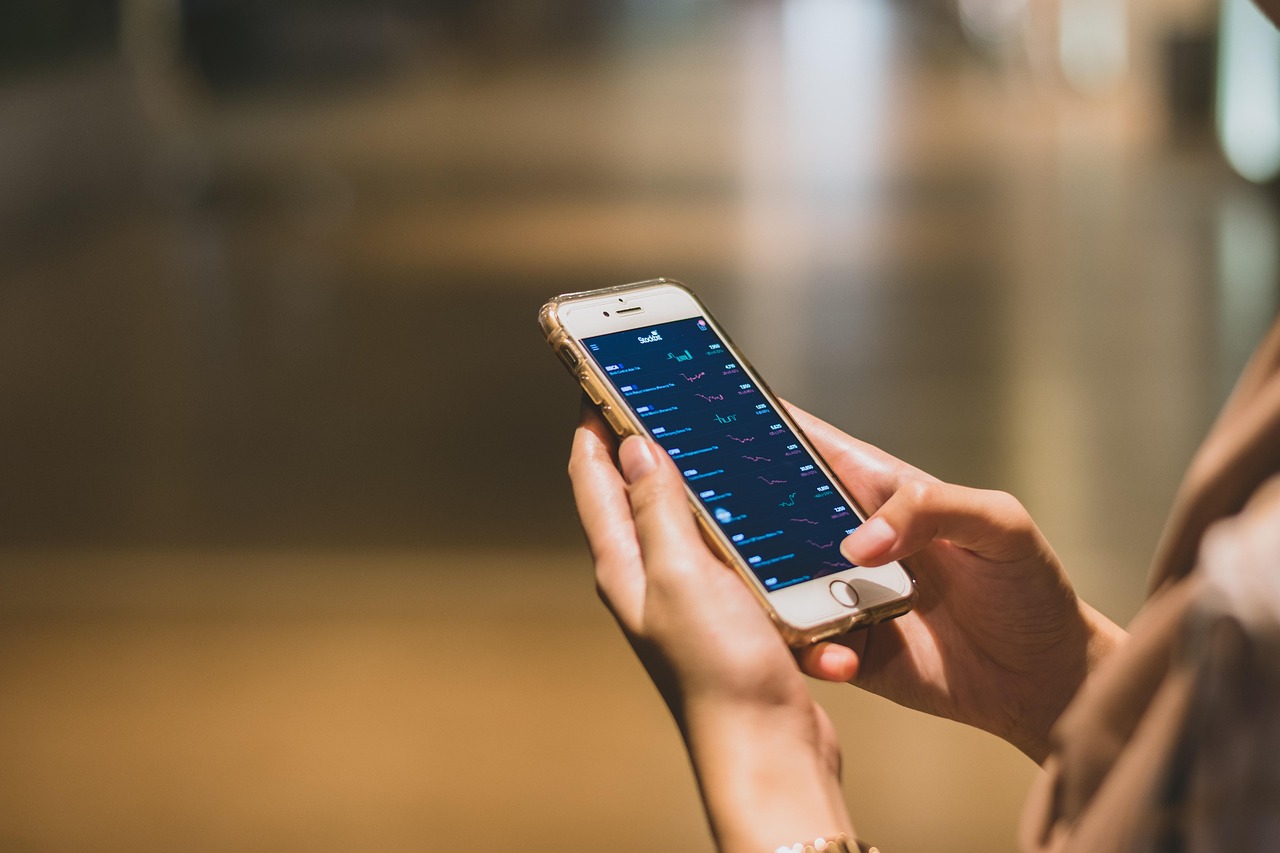
The pitch is beautiful in its simplicity. Download an app, answer a few questions about your risk tolerance, link your bank account, and let the algorithm do the rest. No spreadsheets, no jargon, no late nights reading prospectuses. Your money grows in the background while you live your life. It's the financial equivalent of a slow cooker, and for a generation raised on convenience, it's nearly irresistible.
And to be fair, automation solves a real problem. Most people don't invest because they're intimidated or busy or both. An app that removes that friction gets money into the market that would otherwise sit in a savings account losing ground to inflation. That's a genuine win. But the ease that gets you started is the same ease that can keep you from ever looking under the hood, and that's where the quiet damage happens.
The Fees You Never See
Every automated platform has to make money somehow, and most do it through a layered fee structure that's easy to miss. There's the platform fee, the fund expense ratios, and sometimes a management fee on top. Individually each one sounds trivial, a fraction of a percent. Stacked together over decades, they can quietly shave thousands off your final balance. Because the money leaves in tiny increments you never feel, the leak goes unnoticed until you compare your returns to a simple index fund and wonder why the gap is so wide.
Then there's the allocation itself. Algorithms tend to favor a set-it-and-forget-it mix that doesn't adjust for your changing life. The twenty-five-year-old who could stomach volatility becomes the forty-year-old who can't, but the portfolio doesn't know that unless someone tells it. Left alone, it may hold a risk profile that made sense a decade ago and doesn't anymore.
Automation Without Abdication
The fix isn't to abandon the apps. It's to treat them as a starting point rather than a finish line. Once a year, log in and actually read what you own. Check the expense ratios of the funds you're in and compare them to low-cost alternatives. Look at whether your allocation still matches your timeline and your stomach for risk. If you've had a major life change, a new job, a child, a looming retirement, the portfolio should reflect it.
Automation is a tool, not a strategy. It handles the discipline so you can focus on the decisions. The people who build real wealth over time aren't the ones who never touch their accounts. They're the ones who let the machine do the routine work while they keep an eye on the map. The slow cooker still needs someone to check that it's plugged in.


Primrose Path
Detox teas and juice cleanses promise a fresh start, but the reset often comes with a bill your body and wallet both regret.